


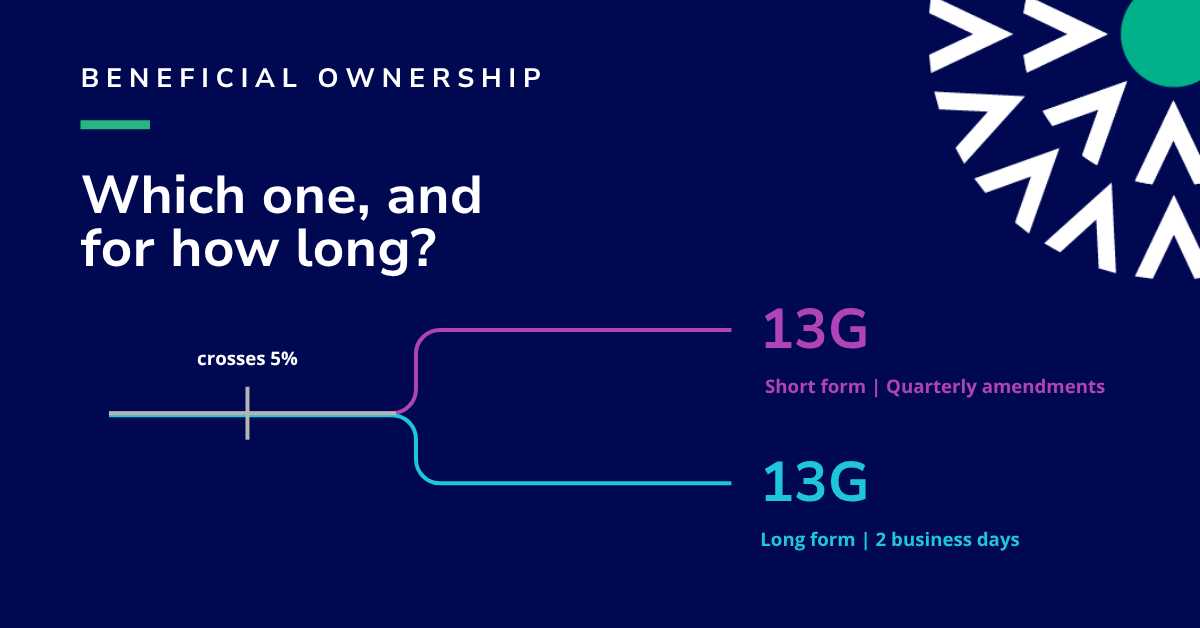


13G vs 13D. That’s the awkward part of beneficial ownership monitoring and reporting. Eligibility for the short form isn’t a one-time determination made when you cross 5%; it’s a continuing condition that depends on what your firm does and says afterwards. A stewardship conversation, a position that drifts past a threshold, an affiliate that starts acting in concert: any of these can quietly move you onto the long form, with a five-business-day clock and a cooling-off period attached.
The rules have moved too. The SEC’s 2023 amendments shortened almost every deadline and replaced the familiar annual February amendment with a quarterly cadence. The February 2025 staff interpretations then withdrew the long-standing position that engagement on compensation, ESG, or general governance topics was safe “without more”… prompting several of the largest index managers to pause their engagement programmes while they reworked their protocols.
Schedule 13D or schedule 13G: the short answer
Both schedules report the same thing: beneficial ownership of more than 5% of a class of voting equity securities registered under Section 12 of the Exchange Act.
The difference is intent, and the cost of getting it wrong is measured in disclosure burden and speed.
- Schedule 13D is the long form. It is the default. It asks for your source of funds, your transaction history, your contracts and arrangements, and, critically, your plans or proposals for the issuer. Amendments are due within two business days of any material change.
- Schedule 13G is the short form. It is an exemption from the default, available only to investors who fit one of three defined categories and who are not holding the securities with the purpose or effect of changing or influencing control. It asks for far less, and for most filers it is amended quarterly rather than within days.
So the question is “can I demonstrate that I qualify for the exemption?”
What does “passive investor” actually mean?
This phrase gets used loosely, and the looseness causes filing errors. It has two distinct meanings.
The narrow, technical meaning.
“Passive Investor” is a defined eligibility category under Rule 13d-1(c). To use it you must hold less than 20% of the class and must not hold the securities with the purpose or effect of changing or influencing control of the issuer. This is the route most non-institutional filers use.
The broad, conceptual meaning.
Every 13G route except the exempt-investor route requires the same underlying certification: the securities were not acquired and are not held for the purpose of, or with the effect of, changing or influencing control.
“Control” here is not a numeric test. It borrows the definition in Exchange Act Rule 12b-2: the power to direct or cause the direction of management and policies, whether through share ownership, contract, or otherwise. It is a facts-and-circumstances analysis of what you have actually done and said, not a statement of what you intended when you bought.
What this rules out.
Nominating your own director slate. Pushing for a sale of the company or a significant block of its assets. Advocating a restructuring. Forming a group with other holders to act together on any of the above.
What the February 2025 guidance changed.
The SEC staff withdrew the older position that engagement on executive compensation, environmental and social topics, or governance matters unrelated to a control contest would generally not, on its own, cost a shareholder its 13G eligibility. That prior guidance was removed, and the staff now takes the view that a shareholder exerting pressure on management to adopt specific governance measures may be seen as attempting to influence control.
The distinction the staff draws is between informing and pressuring. Explaining your views on a topic and how those views may shape your voting decisions is still compatible with 13G. Going further and pressing management to adopt particular measures or policy changes may not be. Explicitly conditioning your support for a company’s director nominees on management making changes you have asked for sits on the wrong side of that line.
The practical consequence was immediate: several of the largest index managers paused their engagement programmes in early 2025 to rework their protocols before resuming. Any firm with a stewardship function should have its engagement scripts and meeting notes reviewed against this standard.
Who qualifies to file 13G? The three routes
| Route | Rule | Who it covers | Conditions |
| Qualified Institutional Investor (QII) | 13d-1(b) |
Registered broker-dealers, banks, insurance companies, registered investment companies, registered investment advisers, employee benefit plans, savings associations, church plans, and parent holding companies or control persons of the above |
Securities acquired in the ordinary course of business and not held with a control purpose or effect |
| Passive Investor | 13d-1(c) |
Anyone who is not a QII |
Holds less than 20% of the class and no control purpose or effect |
| Exempt Investor | 13d-1(d) |
Holders of more than 5% who never made an acquisition subject to Section 13(d) — most commonly pre-IPO holders whose stake predates the issuer’s Section 12 registration |
No control certification required; eligibility is lost by making further qualifying acquisitions |
A note on the exempt route that catches people out: if you held your position before registration and then buy more, you need to reassess. Once your acquisitions over the preceding twelve months aggregate to more than 2% of the class, you can no longer sit on the exempt route and must either qualify under 13d-1(b) or 13d-1(c) or move to Schedule 13D.
Who typically files a 13G?
- Index and passive fund managers: the largest single population of 13G filers, reporting across hundreds of issuers.
- Large active asset managers and registered investment advisers, where holdings are accumulated in the ordinary course for client accounts.
- Bank trust departments and insurance company general accounts.
- Broker-dealer market-making and principal trading desks, where large positions arise from inventory rather than intent. Citadel Securities, for example, files routinely on the 13d-1(c) passive route.
- Public and corporate pension plans.
- Founders, early employees, and venture investors whose stake predates the IPO and who have not added to it since — the classic exempt-investor profile.
- Long-only funds and family offices holding meaningful but sub-20% stakes with no board or strategy agenda.
By contrast, activist funds, strategic acquirers, bidders building a toehold, and anyone running a proxy contest file 13D.
Deadlines and amendment cadence
The 2023 amendments shortened almost every deadline and, most significantly for institutions, moved 13G amendments from an annual to a quarterly rhythm.
Initial filings
| Filer | Initial deadline | Accelerated deadline |
|---|---|---|
| QII (13d-1(b)) | 45 days after the end of the calendar quarter in which ownership exceeds 5% | 5 business days after the end of any month in which ownership exceeds 10% |
| Passive Investor (13d-1(c)) | 5 business days after exceeding 5% | 2 business days after exceeding 10% |
| Exempt Investor (13d-1(d)) | 45 days after the end of the calendar quarter in which ownership exceeds 5% | — |
| Schedule 13D | 5 business days after exceeding 5% | — |
Amendments
All 13G filers: within 45 days after the end of a calendar quarter in which a material change occurred in the information previously reported. Note the two changes here. It used to be annual, and it used to be triggered by any change. It is now quarterly and triggered by material change.
For 2026 that means quarterly due dates of 17 February, 15 May, 14 August, and 16 November.
QIIs, additionally: within 5 business days after the end of a month in which ownership first exceeds 10%, and thereafter after any month-end in which the position moves by more than 5% of the class.
Passive Investors, additionally: within 2 business days of exceeding 10%, and thereafter on any move of more than 5% of the class.
Schedule 13D, for comparison: within 2 business days of any material change. The old “promptly” standard is gone. An acquisition or disposition of 1% or more of the class is treated as material per se; smaller moves may still be material on the facts.
Two operational points worth flagging internally
- February 14 is no longer an annual catch-all. It survives only as the quarterly deadline for Q4 material changes. Teams that built a calendar around a once-a-year February sweep are now under-filing.
- “Material” is undefined for 13G quarterly amendments. The SEC has not specified a threshold. Most firms apply the 1% analogue from Rule 13d-2(a) as a floor and document a judgement for anything below it.
Filing mechanics
Schedules 13D and 13G must be submitted in the SEC’s 13D/G-specific XML-based structured format, a requirement in force since 18 December 2024. The EDGAR cut-off for these schedules is 10:00 p.m. Eastern, extended from the 5:30 p.m. deadline that still governs many other filings. Do not assume a single house cut-off across all your filing types.
What happens if you lose 13G eligibility?
This is the transition that most often goes wrong, because it happens gradually and nobody logs the moment it happened. Eligibility falls away when any of the following occur:
- A control purpose or effect develops, including through the engagement conduct described above.
- A Passive Investor’s stake reaches 20% of the class.
- An Exempt Investor makes qualifying acquisitions crossing the 2% aggregation threshold.
- A QII’s holding stops being in the ordinary course of business.
- A group forms with other holders under Rule 13d-5 whose combined intent is not passive.
Once eligibility is lost you must file a Schedule 13D within five business days of the disqualifying event.
The cooling-off period is the part people miss. From the moment of the disqualifying event until ten calendar days after the Schedule 13D is filed, the reporting person may not vote or direct the voting of the securities, and may not acquire any additional beneficial ownership of the class. A firm that discovers the trigger late has often already voted a proxy or added to the position in the interim, and cannot undo it.
The risks of misfiling
Filing 13G when you were not eligible is a Section 13(d) violation, and the certification makes it worse. QIIs and Passive Investors certify their lack of control purpose on the face of the schedule. An inaccurate certification is not a technical foot-fault; it is an affirmative misstatement in a filing.
Late filings are enforced, in bulk. The SEC has run multiple sweeps against Section 13 and Section 16 delinquencies, charging institutional investors, corporate insiders, and issuers together in single actions, with civil penalties applied per filer. These are strict-liability-style cases in practice: the SEC does not need to show the delay was strategic.
Aggregation errors are the most common technical failure. Beneficial ownership must be computed across all funds, accounts, general partners and control persons, and must include derivatives and convertible instruments exercisable within 60 days. Investment discretion for Form 13F purposes and beneficial ownership for Section 13(d) purposes are not the same concept: a 13F position map is not a 13D/G position map.
Derivatives require a facts-and-circumstances view, not a rule of thumb. The staff’s July 2026 interpretations confirm that a standard cash-settled total return swap, on its own, does not confer beneficial ownership of the reference securities or of shares a counterparty holds to hedge. But arrangements that prevent beneficial ownership from vesting while effectively delivering its attributes can still result in beneficial ownership under Rule 13d-3(b). Structure matters more than instrument type.
Engagement drift is the newest exposure. A stewardship team acting on last decade’s understanding of permissible engagement can quietly disqualify a position that legal and compliance still believe is a clean 13G.
The downstream consequences run beyond the SEC. Missed or inaccurate filings can trigger poison pill provisions, breach investment management agreements and side letters, surface in ODD questionnaires and consultant reviews, and, where a filing is materially misleading, support private claims. For issuers, a 5% holder you know about but who has not filed cannot simply be omitted from the Item 403 beneficial ownership table.
Quick decision sequence
- Do you beneficially own more than 5% of a class of voting equity registered under Section 12? If no, stop.
- Did you acquire any of it after the class was registered? If no, consider the exempt-investor route.
- Are you a QII under 13d-1(b), acquiring in the ordinary course? If yes, and there is no control purpose, 13G on the quarterly cadence.
- Are you below 20% with no control purpose? If yes, 13G on the passive cadence.
- Anything else, or any control purpose at all, Schedule 13D.
Then calendar the deadline against the right trigger date, and set monitoring for the 10% and 5%-movement thresholds.
Current as of August 2026. Reflects the SEC’s 2023 beneficial ownership amendments (compliance required from 30 September 2024), the February 2025 interpretations on shareholder engagement, and the July 2026 Corporation Finance Interpretations on swaps and Schedule 13D disclosure.
This FAQ is general information, not legal advice. Beneficial ownership determinations turn on specific facts, and firms should confirm their filing position with counsel.
Get the checklist
Working through a holding that just crossed 5%? We’ve put the whole assessment into one checklist: trigger test, the three eligibility routes with deadlines, the conduct that costs you 13G status and the amendment cadence to calendar.